China AI map: model labs, chips and robotics beyond ZHIPU and MINIMAX
Quote1,099 words
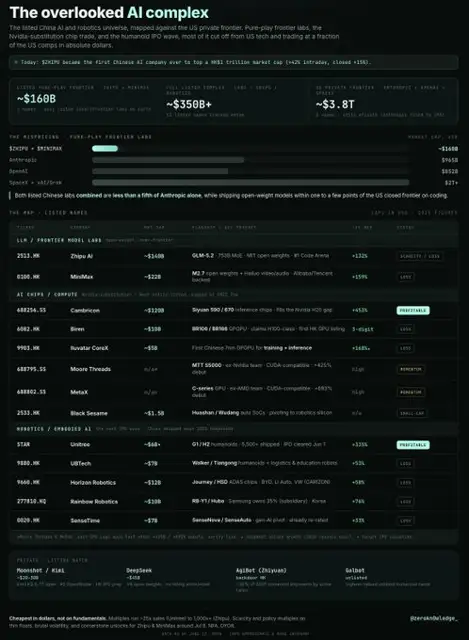
Landscape of Chinese AI exposure in four buckets: LLM labs, AI chips, robotics and a zoom-out. Zhipu plus MiniMax (~$140-175B) are worth under a fifth of Anthropic ($965B), yet multiples are extreme (ZHIPU above 1,000x sales).
Key claims
Zhipu and MiniMax combined ~$140-175B vs Anthropic at $965B
ZHIPU trades above 1,000x its ~$100M 2025 revenue
Unitree 2025 revenue up 335% to RMB 1.7B with ~$288M net profit
Amid the HIP-3 listings of $ZHIPU and $MINIMAX, it's time to take a look at the broader landscape of overlooked opportunities in the AI game.
➊ LLM / FRONTIER MODEL LABS
The only publicly listed pure-play LLM labs with (near)frontier on earth rn are Chinese, and both ship open-weight models that are rapidly catching up with the US behemoths.
1.1 ) $ZHIPU (HK2513): ~$120-155B
First pure-play AI lab to ever IPO (Jan 8), spun out of Tsinghua. Shipped GLM-5.2, a 753B open-weight (MIT) model: 62.1 on SWE-bench Pro, ahead of GPT-5.5, and one point behind Opus 4.8 on FrontierSWE at roughly 1/6 the cost. Up ~25x from IPO with a free float under 6%. 2025 revenue only ~$100M, so this is priced on scarcity, not cash flow. Yet, JPMorgan now models +534% Z AI revenue in 2026, profitable by 2028.
1.2 ) MiniMax (t.co/3TuJZ1qhZO) ~$20B
Alibaba, Tencent and miHoYo backed. Lab behind the open-weight M-series models that rank among the strongest open-source models on coding and agentic benchmarks, plus Hailuo video and audio. Doubled on public listing debut, with public tranche oversubscribed ~1,837x. STAR Market A-share dual listing now in tutoring with CITIC. ~$79M 2025 revenue, ARR over $300M, 70%+ of it overseas.
1.3 ) Private / listing watch:
Moonshot/Kimi (~$20-30B, Kimi K2.6 is a 1T open model, #2 on OpenRouter, restructuring for a HK IPO) and DeepSeek (~$45B, V4 open weights). When either lists, the listed-(near)frontier basket doubles.
➋ AI CHIPS / COMPUTE
China's Nvidia-substitution trade.
One thing to note before we dive in: Most are entity-listed (meaning they're effectively on an export blacklist, requiring any US company to have a special license to sell them anything) and capped at SMIC 7nm (aka cut off from TSMC, meaning they have to manufacture domestically at SMIC, China's top foundry. But SMIC is itself sanctioned and can't buy the most advanced lithography machines).
2.1 ) Cambricon (SS688256) ~$120B
China's only pure-play listed AI chip designer, which posted its first annual profit ever in 2025 with revenue up 453% to RMB 6.5B (~$900M), and a net income of RMB 2.1B (~$306M). It also became the first company to shed the "unprofitable" tag on the STAR board (short for the Science and Technology Innovation Board (科创板) on the Shanghai Stock Exchange). Flagship Siyuan 590 and 670 inference chips fill the gap left by Nvidia's H20. However, it's not necessarily cheap either measured on fundamentals, with multiples at ~100x sales and well over 300x earnings.
2.2 ) Biren (HK6082) ~$10B
First mainland GPU maker to list in HK (the year's first IPO, +76% on debut, retail oversubscribed 2,347x). Now volume-shipping its BR106 and BR166 GPGPUs, which is the line it claims rivals Nvidia's H100. Entity-listed, still deeply loss-making for now.
2.3 ) Iluvatar CoreX (HK9903) ~$5B
The first Chinese designer to mass-produce 7nm GPGPUs for both training and inference, with shipment volumes up 168% in 2025. Revenues at ~RMB 540M against a wider ~RMB 890M loss. Early, but a rare full-stack domestic training option.
2.4 ) Moore Threads (SS688795) & MetaX (SS688802)
The two STAR Market GPU debuts of late 2025, founded by ex-Nvidia and ex-AMD teams running CUDA-compatible stacks. Moore Threads popped 425% on listing, MetaX 693%. Both far from profitable today, and mainly momentum names riding the domestic-compute mandate rn.
2.5 ) Black Sesame (HK2533) ~$1.5B
The smallest, most under-the-radar name. Automotive SoCs (Huashan, Wudang) pivoting hard into robotics and on-device AI silicon. Speculative, but the cheapest play in the group.
➌ ROBOTICS / EMBODIED AI
The next IPO wave.
China shipped most of the world's humanoids in 2025, and the listings are only starting.
3.1 ) Unitree (STAR Market, IPO cleared) ~$6B target
The crown jewel. Cleared its STAR listing hearing June 1 in a record 73 days, the first pure-play embodied-AI A-share listing, and it is profitable: 2025 revenue up 335% to RMB 1.7B (~$235M), ~$288M net profit, 60% gross margin, 5,500+ humanoids shipped (a global volume leader by its prospectus). But watch the risk(s): Q1 2026 adjusted profit fell 52% due to R&D spend, and the patent portfolio is comparably thin (only 262 filings).
3.2 ) UBTech (HK9880) ~$7B
Shenzhen humanoid pioneer, HK-listed since 2023, shipping Walker and Tiangong humanoids plus logistics and education robots. 2025 revenue up 53%, break-even targeted around 2027. Still in loss-making territory.
3.3 ) Horizon Robotics (HK9660) ~$12B
Autonomous-driving AI chips (Journey series, the HSD full stack). Design wins across BYD, Chery, Li Auto and a VW joint venture (CARIZON). 2025 revenue up 58% to RMB 3.76B, yet still making losses. Stock recovered well off its lows tho. The closest thing to a picks-and-shovels ADAS play here.
3.4 ) Rainbow Robotics (KQ277810) ~$10B
The non-China standout. Samsung is the largest shareholder at 35% and folded it in as a subsidiary. RB-series cobots, the RB-Y1 dual-arm, and Hubo humanoids, with a CJ Logistics deployment. 2025 revenue up 76%.
3.5 ) SenseTime (HK0020) ~$7B
Generative-AI pivot (SenseNova, SenseAuto). 2025 revenue RMB 5.0B (~$700M, +33%) with a narrowing loss. Well known and already re-rated, here as a comp, not a hidden gem.
3.6 ) Private / listing watch:
AgiBot (Zhiyuan), a top-2025 humanoid shipper by several tallies (~38% share), is pursuing a backdoor HK listing by taking control of a listed company. Galbot is the highest-valued unlisted humanoid name.
➍ ZOOM OUT
Z AI ($ZHIPU) plus MiniMax ($MINIMAX) combined is worth ~$140-175B, which is less than a fifth of Anthropic alone (recently valued at $965B). Meanwhile OpenAI is sitting at $852B, and SpaceX (now public, xAI + Grok folded in) cleared $2T. On benchmarked capability per dollar, the listed Chinese frontier is dramatically cheaper. The same broadly applies across the chip and robotics names. That said, none of this is necessarily cheap on fundamentals.
of this is not necessarily cheap on fundamentals. Multiples run from ~25x sales at the profitable end (Unitree) to triple and even quadruple digits at the model labs. $ZHIPU alone trades north of 1,000x its ~$100M of 2025 revenue, while Cambricon, the profitable outlier, is sitting around 100x sales.
These are scarcity and policy multiples, leveraged bets on China's self-sufficiency and US export control policy, with thin floats and brutal volatility.
But while most of this is largely speculative, and while there are risks involved here (also keep an eye on unlocks, especially for ZHIPU and MINIMAX), China is definitely cooking.
As we're heading deeper into AI szn, HIP-3 szn and most importantly, US IPO szn, I could definitely see some of these catch a decent bid, especially if those assets become widely accessible (incl. leverage) through Hyperliquid.
NFA but DYOR anon.
QUOTING @zerokn0wledge_
$ZHIPU and $MINIMAX HIP-3 markets (two of the hottest open-weight AI labs btw) are live on Hyperliquid. Trading at a fraction of the US frontier labs, this could be a generational entry. Yet, it's a risky bet. I aped both, and here is why: First, what these markets actually ar
$ZHIPU and $MINIMAX HIP-3 markets (two of the hottest open-weight AI labs btw) are live on Hyperliquid. Trading at a fraction of the US frontier labs, this could be a generational entry. Yet, it's a risky bet. I aped both, and here is why: First, what these markets actually ar